Roshni Jaiswal
VAT Consulting Manager
VAT Consulting Manager
 No dejes pasar la devolución del IVA soportado en otros países de la UE: el plazo termina el 30 de septiembre
Don’t miss out on the refund of input VAT in other EU countries: the deadline is 30 September
Non farti sfuggire il rimborso IVA versata in altri paesi UE: la scadenza è il 30 settembre
Sei un’azienda italiana con partita IVA e nel 2025 hai versato IVA in altri Paesi dell’Unione Europea (ad esempio per viaggi, hotel, eventi e alter spese aziendali)? Potresti avere diritto al rimborso.
EU VAT Refunds: Don’t Miss the 30 September Deadline
Don’t let EU VAT refunds slip past September. This used to be called “8th directive” reclaims and are now dealt with electronically under the title “EVR”- which stands for Electronic VAT Refund
 CJEU Clarifies VAT Treatment of Transfer Pricing Adjustments: Lessons from the Stellantis (Former GMP) Case
The Court of Justice of the European Union (CJEU or the Court) has provided important guidance on the VAT treatment of transfer pricing (TP) adjustments in its recent judgement concerning Stellantis Portugal (formerly General Motors Portugal, GMP) on 13th May 2026 Stellantis Portugal C/2024/C-0603-24.
 Non-EU business that incurred VAT in Ireland? Don’t miss the 30 June deadline
A quick reminder for businesses not established in the EU. If you’ve incurred VAT in Ireland last year, the deadline for any reclaim is 30 June 2026.
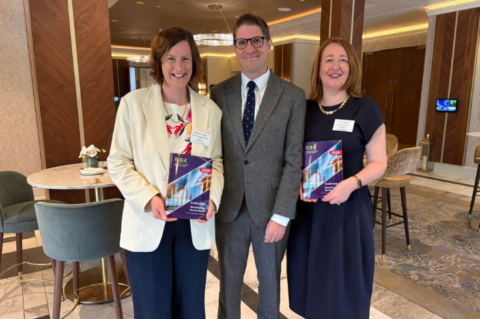 Hub Content: RBK Annual Credit Union Seminar 2026
Welcome to our Hub for the Credit Union Seminar 2026. Take a look back at the content surrounding RBK’s Annual Credit Union Seminar 2026, held on 28 May at The Johnstown Estate.
 Temporary Residents – Be Aware of Unwelcome Gifts
When individuals are considering relocating across borders to Ireland, either as part of a mobility program or in a personal capacity, the focus can often tend to be on payroll taxes, income tax and the taxation of capital gains. What can sometimes be overlooked is the Irish tax treatment of gifts and/or inheritances.
 RBK Budget 2027 Briefing
RBK Chartered Accountants, together with AIB and Athlone Chamber, presented their Budget 2027 Briefing at the Sheraton Athlone Hotel on 7th October 2026.
 RBK Budget Highlight 2027
After weeks of speculation, Finance Minister Simon Harris and Public Expenditure Minister Jack Chambers have delivered Budget 2027. Mr Harris said the budget was being delivered “at a time of major global uncertainty. People need to feel the benefits of economic growth in their own daily lives and, indeed, in their pockets”.
7 October 2026
Budget 2027 Hub
Welcome to our Hub for Budget 2027. Find all the content surrounding RBK’s overview on Budget 2027 and a lookback on our Budget 2027 Breakfast Briefing, held on 7 October at The Sheraton Athlone Hotel.
 Budget 2027 – Rewarding Hard Work & Building Resilience
Budget 2027 was the first Budget delivered by Tánaiste and Minister for Finance Simon Harris, alongside Minister for Public Expenditure Jack Chambers. It provides for an additional €7.1 billion in public spending next year, bringing gross public expenditure to €125.6 billion. On the tax side, the headline measure is a welcome €1.3 billion personal income tax package, a notable change from Budget 2026, which offered little by way of income tax relief.
 European Commission challenges Irish CGT treatment of Government Bonds
The European Commission has opened infringement proceedings against Ireland over the Irish tax treatment of gains arising from the disposal of government bonds issued by other EU Member States and European Economic Area (EEA) countries.
 Global Mobility Meets Transfer Pricing
RBK Chartered Accountants explore the intersection of global mobility and transfer pricing, including the implications of remote working, international assignments, secondments and other cross-border employee activities. We are joined by guest speaker Paul Sutton from LCN Legal, who brings a legal perspective to these issues, with a particular focus on intercompany agreements supporting global mobility, secondments and intra-group services.
 Global Mobility Meets Transfer Pricing
These slides cover the intersection of global mobility and transfer pricing, including considerations relating to remote working, international assignments, secondments and other cross-border employee activities. The presentation also covers legal considerations, including intercompany agreements supporting global mobility, secondments and intra-group services, with input from Paul Sutton of LCN Legal.
1 October 2026
Global Mobility Meets Transfer Pricing
In this webinar, RBK Chartered Accountants explore the intersection of global mobility and transfer pricing, including the implications of remote working, international assignments, secondments and other cross-border employee activities.
Budget 2027: What to Expect
Simon Harris’s first Budget as Minister for Finance comes at a time of strong domestic economic performance but continued international uncertainty. Ireland remains in a relatively strong fiscal position, with high employment, resilient domestic demand and significant corporation tax receipts. However, the international environment remains challenging, with ongoing geopolitical tensions, volatility in energy markets and continuing uncertainty around global trade, in particular US trade policy.
 New Investment Account: What Does It Mean for Irish Investors?
On 31 August 2026, Tánaiste and Minister for Finance, Simon Harris, has announced a new Personal Investment Account as part of its Roadmap for the Taxation of Retail Investment, setting out the proposed framework for a new Investment Account aimed at making investing simpler and encouraging greater participation by Irish households in capital markets.
 Remittance Basis – What’s it all about?
Over the last series of articles, we considered the various concepts of residence, ordinary residence and domicile from an Irish tax perspective. Each is important and has an impact of the taxation of individuals in Ireland, both for income tax and for capital gains tax.
 The Ordinary Residence Trap
In previous commentary we have considered the concepts of “Residence” and “Domicile” for Irish tax purposes. There is a third concept in Irish tax law that can often take the uninformed by surprise, and that is the concept of “Ordinary Residence”. When considering ordinary residence, it’s all about counting years of consecutive tax residence. It’s purely an objective test.
 Public CbCR in Ireland: Is your group ready to publish?
Ireland’s public Country-by-Country Reporting (public CbCR) regime has moved from legislation to live reporting. The first Irish deadlines have arrived for some groups, while calendar-year groups within scope must publish their first report by 31 December 2026.
 Executive Relocation 2026
Welcome to the 2026 edition of “Executive Relocation Ireland”, a guide which is designed to help executives and their families deal with the many issues that arise when moving to or from Ireland. Whether you are taking up a new role in Ireland or moving abroad, a relocation affects almost every part of your financial life. Your tax residence and domicile, how your income and investments are structured, your pension planning and even the timing of your move can all have a lasting effect, and getting the right advice early on can make a real difference.
 Executive Relocation Ireland 2026
Relocating to or from Ireland is one of the biggest financial and personal decisions an executive will make. This guide is aimed primarily at individuals who are relocating to or from Ireland and their employers.
17 July 2026
 Tax Residence – Facts and Fallacies
Unlike the concept of domicile, tax residence for Irish tax purposes is specifically defined in Irish tax legislation. It is a very objective test based on the number of days present in Ireland in a tax year.
 Small parcels, big change: the €3 Customs duty on low-value goods coming into the EU
From 1 July 2026, the European Union will implement a temporary €3 Customs duty per item type on low value consignments (less than €150) imported from outside the EU (including Great Britain).
 Transfer pricing considerations in the context of Statutory Audits
The Irish Transfer Pricing regulations were significantly overhauled for accounting years beginning on or after 1 January 2020, introducing formal documentation requirements.
 Demystifying Domicile
From an Irish tax perspective there are a number of concepts that individuals need to be aware of such as tax residence, ordinary residence and domicile.
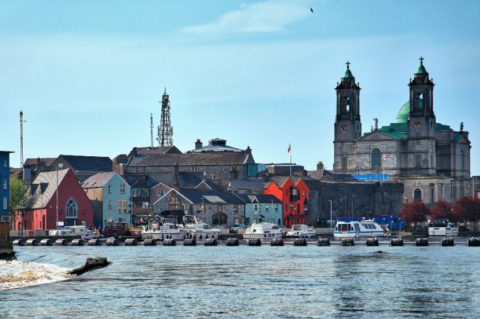 Modernise the Midlands – Living City Initiative
On 17 April 2026, the Tánaiste and Minister for Finance, Simon Harris signed a number of Statutory Instruments to formally designate five additional towns, one of which is Athlone as “Special Regeneration Areas”, under the Living City Initiative (LCI).
 Rocket Science & VAT. Who’d have thought?
Space missions, like VAT, are complex. Getting it right takes time with individual and team effort. There are many stakeholders. And success helps deliver more.
 Have you Heard? VAT Registrations Might Finally be Getting a Little Easier
There’s good news and there are important learnings from a recent decision Tax Appeals Commission case. This decision won’t transform the VAT registration process overnight.
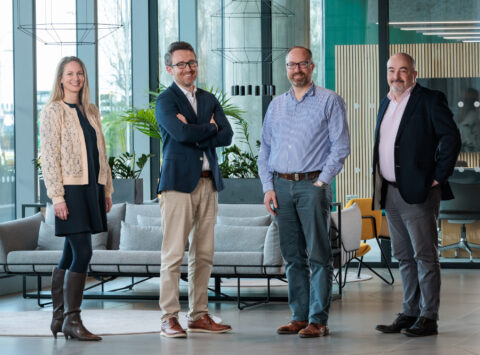 Meet our New Tax Partner & Associate Partners
Congratulations to our newly appointed Tax Partner, Sinead McMahon and Associate Partners, Richard McAufield and John Moore, who strengthen and support RBK’s Tax team in delivering expert guidance to our clients.
 RBK Doing Business in Ireland Guide 2026
RBK Chartered Accountants are pleased to announce the release of our Doing Business in Ireland Guide 2026. This guide is an excellent resource for businesses already operating in Ireland, considering establishing a presence here, or exploring investment opportunities.
 Doing Business in Ireland 2026
Stable, competitive, secure and pro-business, Ireland is a committed member of the EU single market.
23 March 2026
 Finance Bill 2025
The Finance Bill 2025, published on 10 October 2025, gives legislative effect to the measures announced in Budget 2026 and introduces a series of refinements across Ireland’s tax system. The Bill largely builds upon reforms introduced in the last couple of years while advancing specific updates in several areas – including personal taxation, business incentives, housing, pensions, and environmental levies.
 Finance Bill 2025 – Employment and Individual Taxation
The personal tax measures introduced under Finance Bill 2025 were limited. For employees, the changes provide only a very small piece of financial relief.
 Finance Bill 2025 – Corporation Tax
The Finance Bill 2025 introduces a series of targeted refinements to Ireland’s corporation tax framework. While much of the legislation consolidates measures introduced in recent years, there are important developments in areas such as R&D, international tax compliance and environmental investment.
 Finance Bill 2025 – Property
The property related provisions in the Finance Bill 2025 continue the Government’s stated aim on housing supply and affordability. However, the below measures may not have a large enough impact to really affect the current state of housing availability
 Finance Bill 2025 – Pensions
The Finance Bill 2025 continues Ireland’s pension reform programme. Its main focus is to put in place the final tax and administrative rules needed for the new Automatic Enrolment (AE) Retirement Savings System.
 Finance Bill 2025 – VAT
The Finance Bill 2025 introduces a number of rule changes to Ireland’s VAT regime. These are aimed to deliver on measures announced in the Budget speech, as well as clarifying and updating other VAT rules on some additional points
 RBK Budget 2026 Briefing
 RBK Budget 2026 – Tax analysis
“We have to strike the right balance between increasing investment and moderating the growth in day to day spending. This is why our tax changes must be of a certain value and no more. Now is the time to steady ourselves on the path to the future.”
8 October 2025
 Budget 2026 – Seeking Stability in Uncertainty
Budget 2026, amounting to €9.4 billion, was presented as a “sensible budget” aimed at maintaining economic stability and strengthening Ireland’s resilience amid global uncertainty.
 RBK Budget highlight 2026
Finance Minister Paschal Donohoe has unveiled the details of Budget 2026, including a surprise change to how derelict properties are taxed, a cut to the hospitality VAT rate, and an extension of the rent tax credit for another three years.
7 October 2025
 VAT in the Digital Age (ViDA)
On 25 March 2025 the ViDA package was published in t he Official Journal of the EU marking a pivotal moment for VAT in the EU.
 VAT in the Digital Age
On 25 March 2025 the ViDA package was published in the Official Journal of the EU marking a pivotal moment for VAT in the EU. ViDA is a set of legislative reforms aimed at modernizing the EU’s VAT system to better align with technological advancements and address challenges such as VAT fraud and the platform economy.
18 March 2025
 Revenue publishes R&D Pre-filing Notification Forms
For accounting periods commencing on or after 1 January 2024, certain companies must notify the Revenue Commissioner of their intention to file a R&D Tax Credit claim.
Temporary Residents – Be Aware of Unwelcome Gifts
When individuals are considering relocating across borders to Ireland, either as part of a mobility program or in a personal capacity, the focus can often tend to be on payroll taxes, income tax and the taxation of capital gains. What can sometimes be overlooked is the Irish tax treatment of gifts and/or inheritances.
RBK Budget 2027 Briefing
RBK Chartered Accountants, together with AIB and Athlone Chamber, presented their Budget 2027 Briefing at the Sheraton Athlone Hotel on 7th October 2026.
Budget 2027 Hub
Welcome to our Hub for Budget 2027. Find all the content surrounding RBK’s overview on Budget 2027 and a lookback on our Budget 2027 Breakfast Briefing, held on 7 October at The Sheraton Athlone Hotel.
Budget 2027 – Rewarding Hard Work & Building Resilience
Budget 2027 was the first Budget delivered by Tánaiste and Minister for Finance Simon Harris, alongside Minister for Public Expenditure Jack Chambers. It provides for an additional €7.1 billion in public spending next year, bringing gross public expenditure to €125.6 billion. On the tax side, the headline measure is a welcome €1.3 billion personal income tax package, a notable change from Budget 2026, which offered little by way of income tax relief.
At RBK, we provide our clients with high-quality technical and commercial solutions that are responsive, relevant and practical.